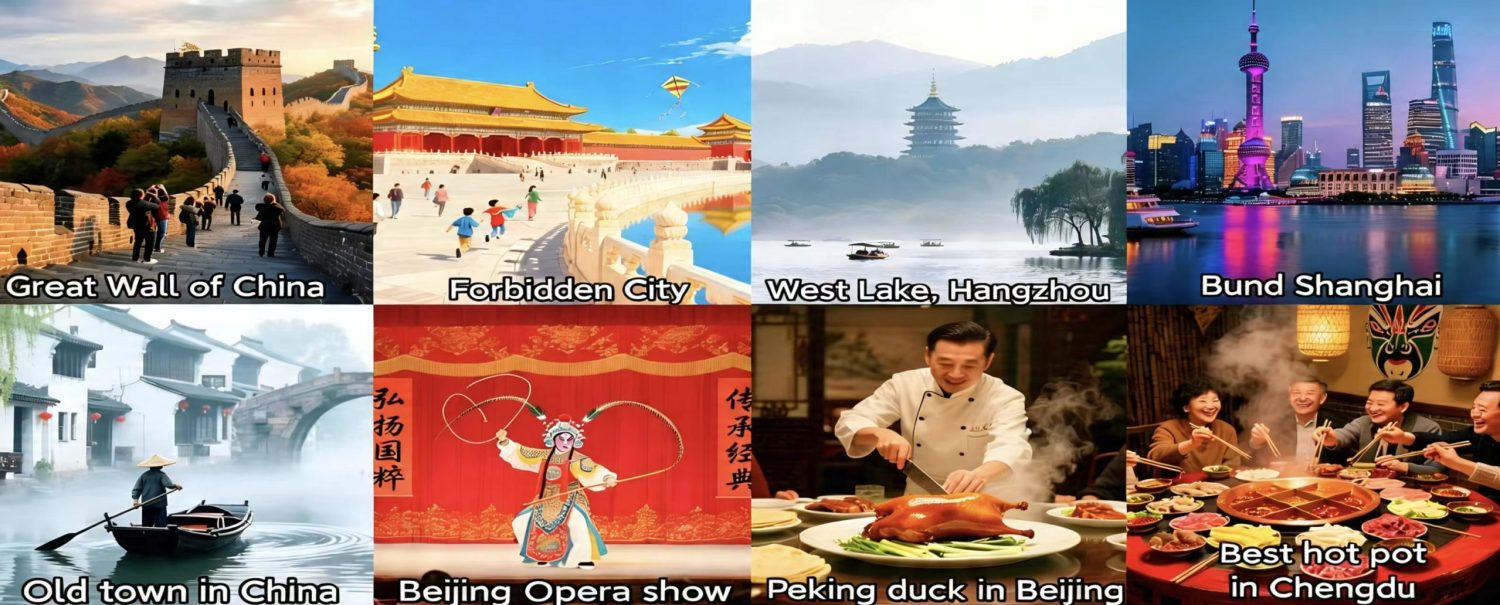
If you’ve visited China recently, you’ve likely watched everyone around you tap a phone while you fumble with a plastic card. China mobile payment trends have erased cash from most cities so completely that bringing a wallet feels almost quaint. Here’s what’s actually happening on the ground.
How China mobile payment trends reshape daily life
The shift runs far deeper than convenience. Street vendors in Chengdu, night-market stalls in Xiamen, even the chestnut seller on Wangfujing Street in Beijing — all run QR terminals now. Alipay and WeChat Pay function less like payment apps and more like the operating system of Chinese retail. Small merchants who resisted them two years ago are now the genuine exception, not the rule.
What surprises visitors most is the raw speed. A transaction takes three seconds. No chip, no PIN, no signature. The vendor confirms on a tiny screen, hands you the baozi,and you’re done. It feels almost anticlimactic after the old drama of swiping and signing.

Why China mobile payment trends spread overseas
The second wave hits foreign users directly. Alipay and WeChat Pay now accept linked Visa and Mastercard accounts, so you can scan a QR code in Shanghai using an international card registered in an app — no currency exchange, no cash drawer. Cross-border QR transactions cleared over 2.4 billion in 2025, driven largely by tourists and short-term visitors who skip the bank queue entirely.
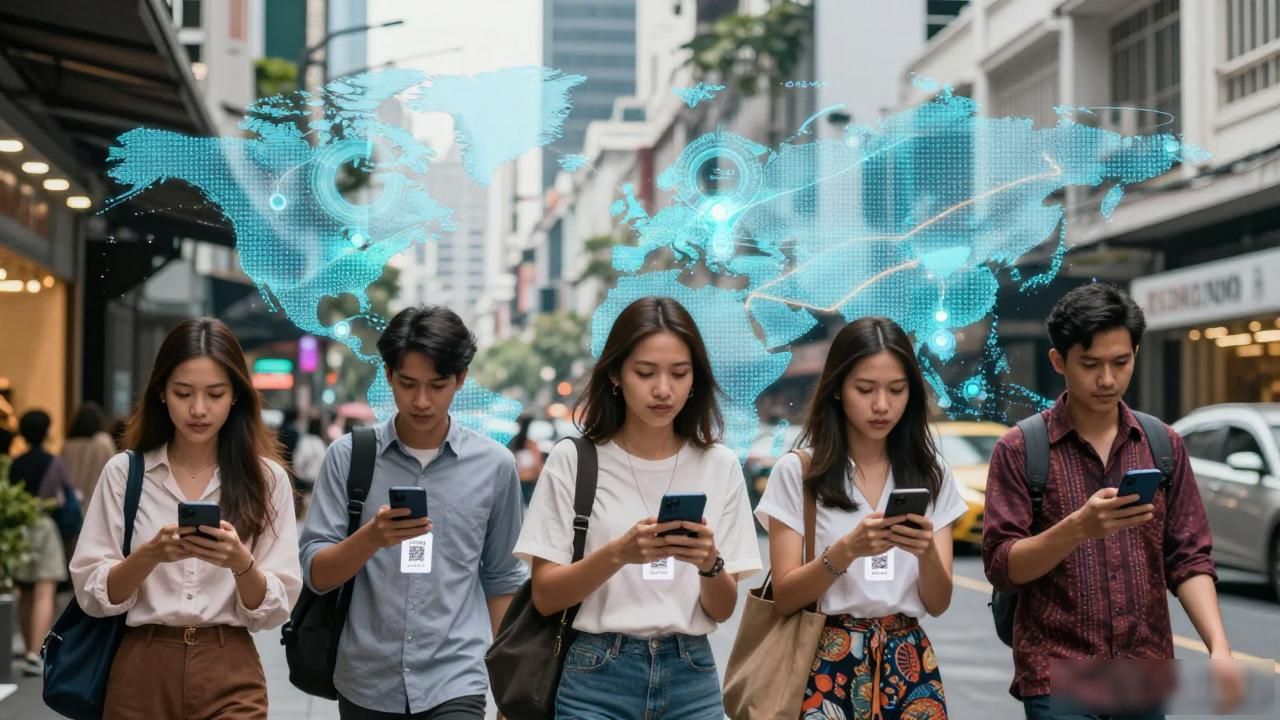
A quieter shift is landing across Southeast Asia. Shoppers in Manila and Bangkok scan familiar-looking QR codes, but the backend routing increasingly touches Chinese payment infrastructure. That export of rails is accelerating faster than most industry forecasts projected two years ago.
Whether you’re planning a trip or studying digital economies, these shifts genuinely matter. China mobile payment trends are no longer a purely domestic story — they’ve become the blueprint other markets quietly copy. The next QR code you scan in a Thai noodle shop carries that ripple effect right in its pixels.