I’ve spent years helping travelers sort out insurance before heading to China, and the honest answer is: yes, you need it, but not just any policy. Medical costs at foreigner-designated hospitals in Beijing or Shanghai can hit thousands of dollars for a routine ER visit, and if your flight gets cancelled, you’re paying your own way home. The right policy fills exactly those gaps.
What travel insurance covers in China

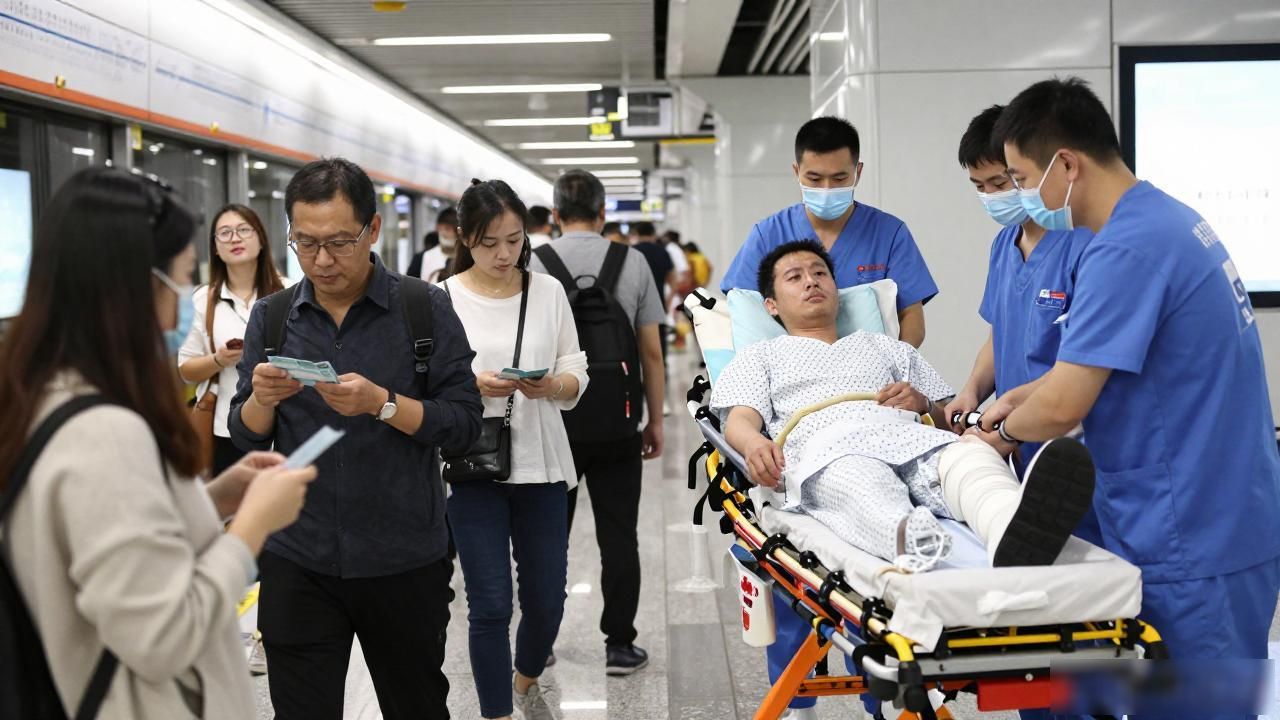
Most solid plans include emergency medical evacuation, which matters far more than tourists realize. Break a hip in Xi’an and local treatment isn’t sufficient, so you’re flying to a better facility or back home. Also check for coverage on public transit accidents, because China’s subway and bullet-rail systems are where most minor tourist injuries happen every single season.
Trip cancellation and interruption coverage protects the non-refundable flights and hotel bookings you’ve already paid for. I’ve watched people lose over $1,500 to a visa delay or a sudden illness right before departure. Look for a “cancel for any reason” add-on if you can stretch the budget; it costs about fifty percent more on top of the base plan but saves real money when something goes sideways.
Does travel insurance cover China medical
This is where most people get genuinely confused. Standard health insurance back home in the US, UK, or EU does not apply in China. You’re paying out of pocket at every single clinic. That’s why medical coverage of at least $50,000 is the bare minimum I recommend for any China trip, regardless of how short the stay is.
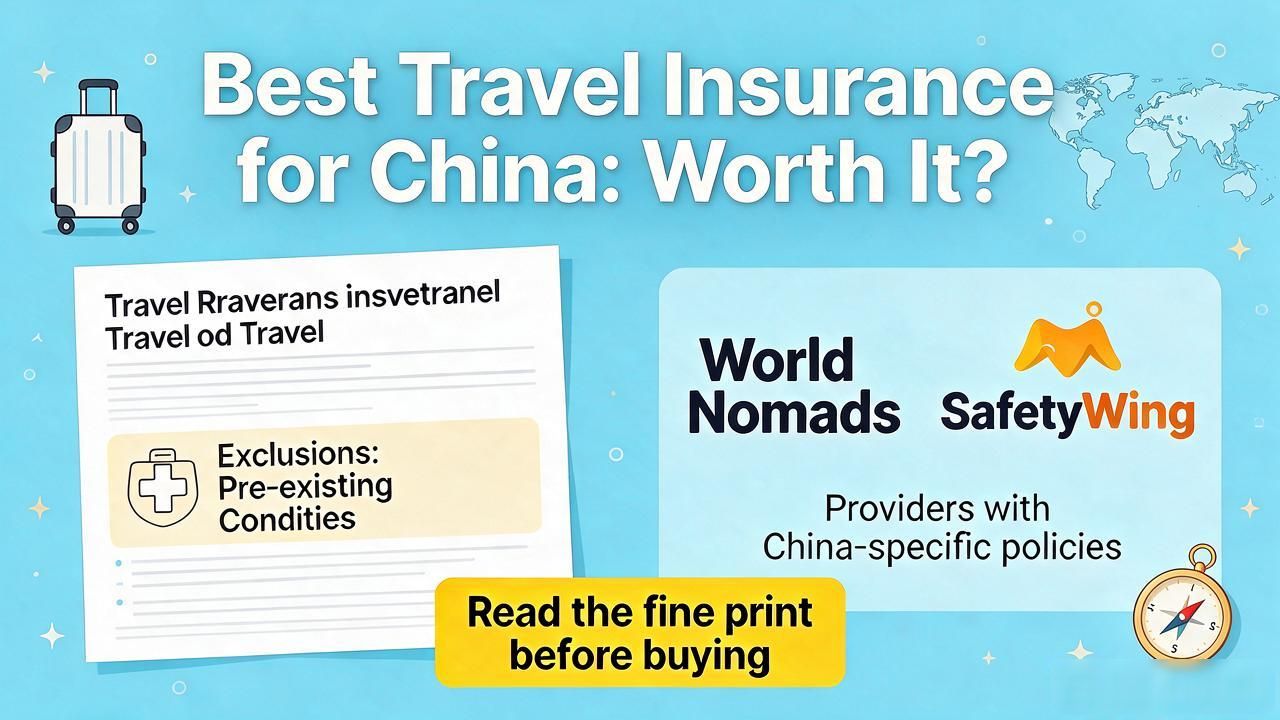
One thing that catches people off guard: pre-existing condition exclusions. If you manage a chronic condition, read the fine print before you buy. Some plans exclude it entirely, others tuck in a waiting period. China-specific policies from providers like World Nomads or SafetyWing tend to spell this out more clearly, so compare a few before committing.
For a two-week China trip, the sweet spot sits between fifty and ninety dollars. You’re not buying a luxury product; you’re buying protection against a $4,000 hospital bill and a missed connection home. Pick one policy, verify the medical provider network near where you’ll actually stay, and keep that document in the same pocket as your passport.